
Linking a budgeting app to your bank account can feel like a superpower: your transactions flow in automatically, budgets update in near real time, and your net worth becomes easier to see at a glance. It can also feel uncomfortable because “automatic” usually means “shared,” and even the best syncing systems sometimes break, duplicate, or miscategorize data.
This guide walks through the pros and cons of using a budgeting app that links to bank account, what to look for before you connect anything, and practical ways to reduce risk while still getting the benefits.
What it means when a budgeting app “links” to your bank account
A bank-linked budgeting app connects to one or more financial institutions (checking, savings, credit cards, loans, investments) and imports account balances and transactions so you do not have to enter them manually.
Depending on the bank and the app, linking may be done via:
- Direct bank authorization (OAuth-style login) where you authenticate with the bank and approve access.
- Data aggregators that specialize in connecting apps to thousands of institutions.
In most consumer budgeting use cases, the app is pulling data (transactions, balances) rather than moving money. Still, you should always verify what permissions you are granting.
Pros of a budgeting app that links to bank account
For many households, bank linking is the difference between “I tried budgeting once” and “I actually stick with it.” Here are the most meaningful advantages.
1) Less manual work, more consistency
Manual tracking fails for a predictable reason: it is tedious. When transactions import automatically, you spend your time reviewing and deciding (Is this “Groceries” or “Dining”?) instead of typing.
That shift matters because consistency is what makes budgets useful.
2) Faster awareness of spending patterns
When your spending is imported as you go, you can catch drift early, like subscriptions you forgot, a restaurant week that got out of hand, or a category that is consistently underestimated.
That feedback loop is hard to replicate with monthly “download a CSV and hope” routines.
3) Better cash flow visibility across multiple accounts
If you have multiple checking accounts, credit cards, or a mix of personal and joint accounts, bank linking can make day-to-day cash flow easier to understand in one place.
Instead of asking:
- “Do I have enough in checking?”
- “What is still pending on my credit card?”
- “When do bills hit?”
You can focus on decisions with a consolidated view.
4) Fewer missed bills (when paired with reminders)
Many budgeting tools can use transaction history and due dates to help you remember recurring payments.
Even if you already use autopay, reminders help prevent surprises, like annual renewals and quarterly insurance bills.
5) Easier reconciliation and cleaner reports
When transactions are imported, it becomes easier to build reports you can trust, like:
- Spending by category over time
- Income versus expenses
- Trends in discretionary spending
- Debt payoff progress
The key is still review, but importing gives you the raw material.
6) Net worth tracking becomes realistic
Net worth is simple math, but it is annoying math if you update it by hand. Linking makes it much easier to track assets and liabilities (and to notice when debt is trending the wrong direction).

Cons (and real risks) of linking your bank account
Bank linking is convenient, but it is not free of tradeoffs. These are the most common issues people run into.
1) Privacy tradeoffs and data sharing concerns
When you link accounts, you are sharing financial data with a third party (the app, and sometimes their connectivity partners). That can include transaction details, merchant names, and balances.
Before linking, look for clear answers to questions like:
- What data is collected?
- Is data used for advertising or sold?
- Can you delete your data and unlink accounts?
For broader consumer guidance on financial data rights and risks, the CFPB’s consumer resources are a useful starting point.
2) Security exposure if your device or account is compromised
A budgeting app is only one part of the security picture. The biggest real-world risks often come from:
- Weak or reused passwords
- Lack of multi-factor authentication
- Phishing or malware on a device
The FTC’s guidance on avoiding phishing is worth reviewing if you have not looked at it recently.
3) Sync problems (connections can break)
Even excellent bank connections can fail temporarily due to:
- Bank maintenance
- Security changes and reauthorization requirements
- Multi-factor authentication resets
- Institution-specific limitations
This is frustrating because it can create blind spots right when you need clarity.
4) Duplicate, pending, or missing transactions
Imported data is not always clean:
- Some systems import a pending transaction and later import the posted one.
- Refunds can look like new spending.
- Transfers between your own accounts can be misread as income or expense.
If you rely on budgets without review, these quirks can cause “false alarms” or hide real overspending.
5) Categorization errors can undermine trust
Automatic categorization is helpful, but it is not perfect, especially for:
- Big-box stores (mixed groceries, household goods, pharmacy)
- Online marketplaces
- Local merchants with unclear names
- Shared purchases that need splitting
If you never correct categories, reports become unreliable, and the app starts to feel “wrong,” even when the underlying data is fine.
6) Not every account will connect (or stay connected)
Smaller credit unions, niche lenders, certain investment platforms, and some business accounts can be difficult to link.
If your financial life depends on one institution that does not sync well, manual tracking or a hybrid approach may be better.
Manual budgeting vs bank-linked budgeting (quick comparison)
No single method is best for everyone. Here is a practical way to compare the two approaches.
| Factor | Bank-linked budgeting app | Manual/spreadsheet budgeting |
|---|---|---|
| Time required | Lower day-to-day entry, higher review/cleanup | Higher data entry, moderate review |
| Accuracy over time | High if you reconcile and recategorize | High if you record consistently |
| Privacy | More data shared with third parties | More private (data stays local) |
| Real-time visibility | Strong | Usually delayed |
| Error types | Duplicates, miscategorization, sync gaps | Missed entries, inconsistent logging |
| Best for | Busy households, multiple accounts, goal tracking | Privacy-first users, simple finances, hands-on trackers |
What to check before you link your bank account
If you are evaluating a budgeting app that links to bank account, these checks will help you avoid most unpleasant surprises.
Security and permissions
Focus on what you can verify.
- Multi-factor authentication support for your budgeting account
- Read-only access (typical for budgeting apps, but confirm)
- Clear permission prompts when linking
- Session and device controls (ability to log out devices, reset access)
Privacy policy and data handling
Look for plain-language answers on:
- Whether data is used for advertising
- Whether data is shared with partners, and why
- Data retention and deletion options
Reliability features that prevent “budget drift”
The best bank-linked experience is not just importing data, it is helping you correct it.
Prioritize apps that offer:
- Transaction review and recategorization
- Account reconciliation tools
- Alerts and reminders for unusual activity, bills, or thresholds
- Exportable reports so you are not locked in
How to reduce risk when using a linked budgeting app
You can get most of the convenience benefits while meaningfully reducing downside.
Start small with a “minimum effective linking” approach
Instead of linking everything on day one, start with:
- One primary checking account
- One primary credit card
Once you are confident in categorization and sync quality, add savings, loans, and investments.
Use strong authentication habits
A budgeting app becomes part of your financial perimeter.
- Use a unique, long password (a password manager helps)
- Turn on multi-factor authentication wherever available
- Keep your phone and computer updated
Review imported transactions weekly
Bank linking reduces typing, not responsibility.
A simple weekly routine (10 minutes) prevents most issues:
- Confirm categories for the biggest transactions
- Mark transfers correctly
- Split mixed purchases when needed
- Check for duplicates or missing merchants
Reconcile monthly for clean reporting
If your app supports it, reconcile so your reports match reality. Reconciliation is what turns “pretty charts” into numbers you can trust.

Who should (and should not) use a bank-linked budgeting app
A bank-linked app is a strong fit if you:
- Want budgeting to be sustainable with minimal daily effort
- Have multiple accounts or shared household spending
- Want ongoing reporting, alerts, and trend insights
A manual approach may be better if you:
- Are extremely privacy-sensitive and prefer offline control
- Have one simple account and very predictable spending
- Hate dealing with categorization cleanup and sync issues
Many people end up with a hybrid: link major accounts, track cash manually, and do a quick weekly review.
Where MoneyPatrol fits
MoneyPatrol is designed for people who want a single place to manage day-to-day finances. It includes core capabilities that matter specifically for bank-linked budgeting:
- Expense tracking and budgeting tools
- Bill and debt tracking
- Income management
- Investment tracking
- Credit score monitoring
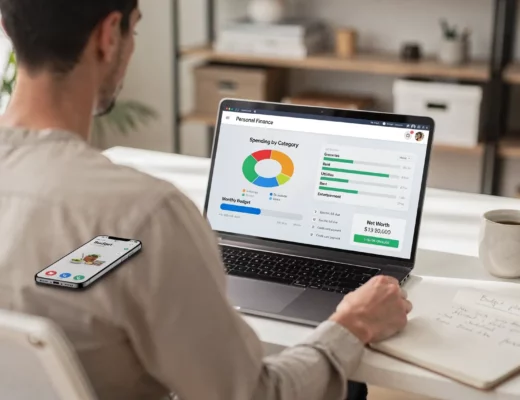
- A personal finance dashboard
- Customizable alerts and reminders
- Account reconciliation and detailed reports
- Connectivity to thousands of financial institutions
If you are comparing options, you can explore MoneyPatrol here: MoneyPatrol. For a broader view of the platform positioning as a free budgeting tool, see: best free budgeting app.
Frequently Asked Questions
Is it safe to use a budgeting app that links to bank account? Safety depends on the app’s security practices and your own habits. Use multi-factor authentication, strong unique passwords, and review the app’s privacy policy and permissions before linking.
Will a bank-linked budgeting app let me move money or pay bills? Many budgeting apps primarily pull data (transactions and balances) for tracking. Always check what permissions you are granting during linking, since capabilities vary by app and institution.
Why do linked budgeting apps sometimes show duplicate transactions? Duplicates often happen when pending transactions later post, or when a bank sends updates in a way that creates two entries. A weekly review and reconciliation helps keep reports accurate.
Do I still need to track spending if everything is linked? Yes. Linking automates importing, not decision-making. You still need to review categories, handle transfers, and confirm that budgets reflect your priorities.
What if my bank will not connect to the app? Some institutions have limited support or require periodic reauthorization. If your primary bank will not connect reliably, consider a hybrid workflow (manual import for that account, linking for others) or a different provider.
How often should I review my transactions in a linked app? Weekly is a practical minimum for most people. It keeps categories clean, catches duplicates, and prevents budget surprises.
Try a bank-linked budgeting workflow (without guesswork)
If you want the convenience of automatic importing, plus tools to stay organized with alerts, reports, and reconciliation, you can try MoneyPatrol’s free personal finance dashboard at moneypatrol.com. Connect one account first, review weekly, then expand from there once you trust the data.


 Our users have reported an average of $5K+ positive impact on their personal finances
